Global Import Data Price Trends You Need to Know
2026-08-26
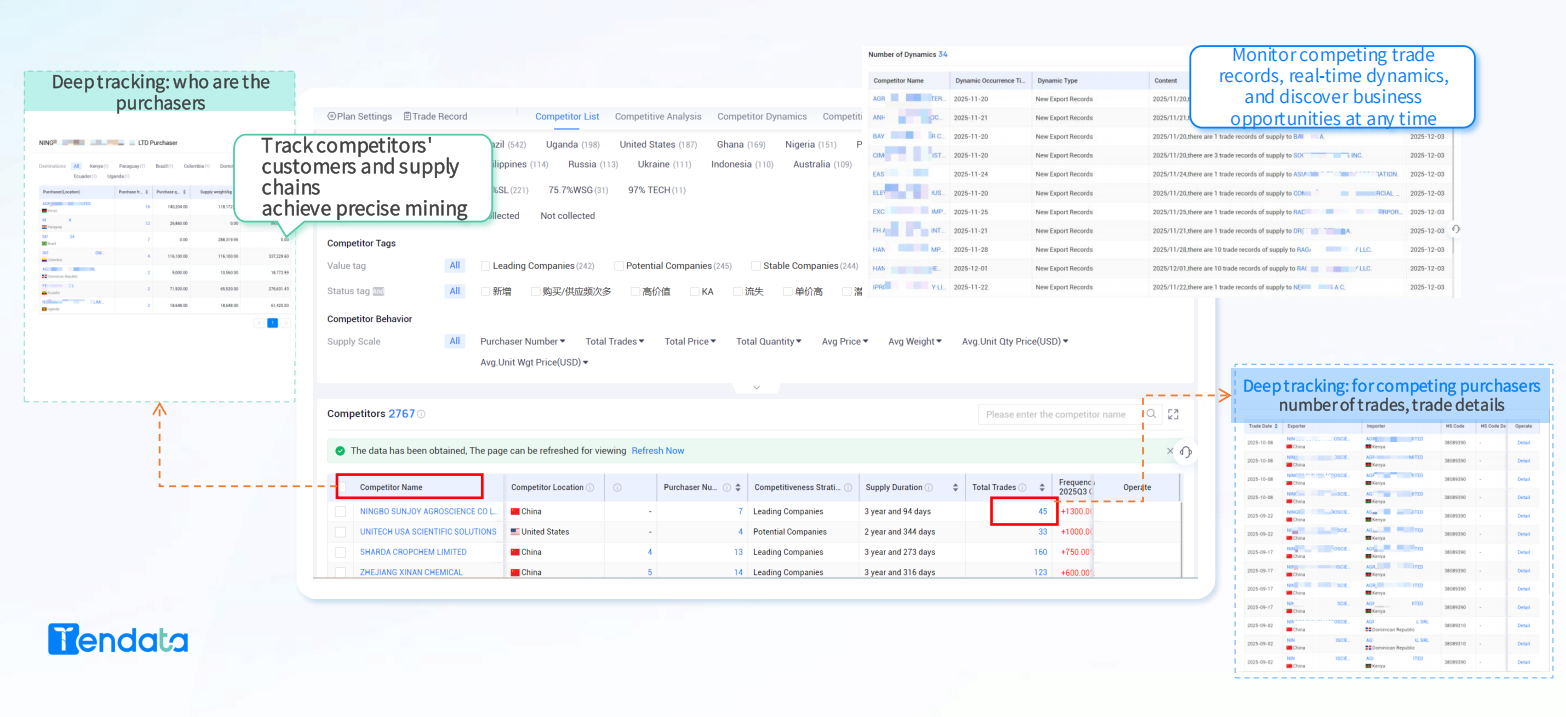
A customs record is more than a compliance document—it's a pricing fingerprint. When you aggregate millions of them, global import data price trends start to speak: which suppliers are quietly raising rates, where freight costs are cooling, and how tariff shifts ripple through landed costs. Most importers only see the invoice after the fact. Tendata puts that intelligence in your hands before you commit to a purchase order. Here are the key price movements reshaping global trade right now.
Why Your Import Bill Is Rising Faster than Any Published Index
The gap between your actual import costs and the official numbers isn't a glitch—it's structural. Published indices smooth out volatility by using fixed baskets and lagging price samples, but your bill reflects real-time freight rates, currency swings, and the surcharges that carriers add without notice. A single container from Shanghai to Rotterdam can spike 40% in a month due to equipment shortages or a canal disruption, while the index barely shifts because it averages that route with cheaper lanes or uses contractual rates that haven't renewed yet.
Then there's the invisible inflation inside the invoice: demurrage, detention, peak-season surcharges, low-sulfur fuel fees, and the quiet reclassification of cargo to a higher tariff code. These line items rarely appear in any consumer or producer price measure, yet they compound weekly. Importers who rely on published indexes to forecast budgets end up under-allocating by double digits, because the indexes are designed to track broad economic trends, not the granular, shipment-level realities you pay for.
What makes it worse is the feedback loop. When your bill rises faster than the index, you cut orders or delay shipments, which reduces capacity utilization and prompts carriers to raise rates on the remaining cargo—again, ahead of any index update. By the time the published number catches up, you've already absorbed three rounds of increases that were never captured in the data. That lag is precisely why your import bill keeps running ahead of the charts that claim to measure it.
The Freight Factor: How Shipping Costs Rewrite Global Price Data
A shipping invoice is rarely just a logistics charge anymore. By the time container rates double or triple on busy lanes like Shanghai–Los Angeles, the extra cost is already baked into the landed price of imported goods. That means two identical products—one made locally, one shipped across the Pacific—can show very different inflation footprints in official data, even when their production costs are similar.
The distortion deepens because most price indexes capture freight at different stages. Some record goods at the factory gate, others at the port of entry. When rates swing sharply, the gap between those two points widens into a meaningful wedge. A country that imports heavily by sea may suddenly appear to have a hotter consumer price index than its domestic wage and rent data alone would suggest, simply because the ocean leg became more expensive.
That hidden freight layer rewrites comparative price levels too. Economists trying to measure purchasing power parity across borders often use retail prices that already include shipping. If one nation sits next to a major manufacturing hub and another is an island dependent on long-haul routes, exchange-rate benchmarks can drift from the underlying cost of living. In effect, freight costs become an unspoken tax that inflates some price data while leaving others untouched, making global comparisons less stable than the headline numbers imply.
Currency Volatility: The Silent Changer of Cross-Border Price Tags
A shopper in Toronto sees a camera listed at $1,200 on a U.S. site, but by the time the payment clears three days later, the final charge is $1,237. The product never changed, and neither did the sticker price. What moved was the currency pair behind the scenes. For any business selling across borders, exchange rates act as an invisible hand that can quietly inflate or shrink a price tag without a single manual edit.
Most cross-border sellers don't update their displayed prices every hour. They set a base currency, then let a conversion tool do the work. If the euro strengthens against the dollar overnight, a German buyer suddenly pays more for the same U.S. software subscription, even though the U.S. company's revenue in dollars remains flat. This disconnect creates a strange pricing limbo: list prices appear stable, but actual transaction values drift with the market. Some companies try to tame this by adding a buffer to their exchange rate, while others switch to local-currency pricing and absorb the risk themselves. Neither approach is perfect, and both can leave one side of the transaction feeling shortchanged.
Over time, this quiet churn reshapes buyer behavior. A customer who notices the same item costing 8% more in their currency than it did last month may delay the purchase or look for a local alternative. On the seller's side, finance teams start to treat currency volatility as a cost of doing business, not a rare shock. The real takeaway is that cross-border price tags are never truly fixed—they are live estimates dressed up as static numbers.
Regional Divergence: Why Import Prices Don't Move in Lockstep
When a currency shifts, the expectation is that import costs adjust uniformly across every port and warehouse. Yet real-world data rarely shows such clean synchronization. A weaker exchange rate might lift landed prices in one region within weeks, while another area sees barely a ripple for months. This unevenness stems from local supply chains, inventory buffers, and the bargaining power of dominant distributors. Coastal hubs with direct container traffic often absorb currency moves faster than inland markets reliant on secondary trucking and rail links, where fuel surcharges and intermediate markups dampen the pass-through.
Contract structures add another layer of friction. Large retailers frequently lock in annual or semi-annual purchase agreements, insulating their shelf prices from short-term exchange volatility. Smaller importers without such leverage must renegotiate more often, creating pockets of faster adjustment. Meanwhile, regional competition plays a quiet but decisive role: if a local market is dominated by two or three importers who choose to hold prices steady to protect market share, even a sharp currency drop may not translate into higher consumer-facing tags until one competitor breaks ranks.
Transportation networks and warehousing costs further splinter the response. A region with congested ports and expensive last-mile delivery will see import prices driven by logistics bottlenecks rather than pure exchange rates. In contrast, a region with ample storage and low distribution costs can absorb temporary cost spikes by drawing down existing stock. The result is a patchwork of price movements that defies any single national average, forcing businesses to track regional import indices rather than rely on headline figures.
Beyond Tariffs: The Hidden Charges Hiding in Import Price Trends
Most import price indices still treat tariffs as the headline variable, but the real erosion of margin often comes from charges that never make it into the official unit value. Port congestion fees, container demurrage, fuel surcharges, and destination handling costs get buried in freight invoices or broker line items, not in the customs declaration. As a result, a product can look competitively priced on paper while the landed cost tells a very different story.
These hidden charges don't move in sync with tariff schedules. A tariff hike may be announced months in advance, giving buyers time to adjust sourcing, but a sudden spike in storage fees at a congested terminal can hit the same shipment with no warning. Currency conversion spreads and payment processing fees, often seen as minor, compound across thousands of transactions and quietly reshape the real import trend.
Ignoring them leads to distorted forecasts. Procurement teams that rely only on customs data may think inflation is cooling, while their logistics invoices show the opposite. The gap between the published import price and the actual cost to get goods to the warehouse is where many supply chain surprises are born.
From Data Noise to Signals: Reading Import Prices Like a Buyer, Not a Bystander
Import price indices often look like a tangle of currency swings, tariff shifts, and seasonal freight spikes. A bystander sees volatility and waits for it to settle. A buyer, by contrast, treats each movement as a question worth asking. Was that uptick driven by a single supplier changing terms, or by a broader shift in raw material costs? Did exchange-rate movement mask an actual price decline? The answer changes which lever to pull.
Seasoned purchasing teams build their own filters. They compare landed costs across three or four origin countries instead of trusting one headline number. They track not just the invoice price but the real cost after duties, logistics, and payment terms. When a data point looks like noise, it often becomes a signal once you overlay supplier lead times and contract renewal dates. A delayed adjustment in one HS code can reveal a supplier absorbing costs—or preparing to pass them on.
Over time, this stance turns import price reports from after-the-fact summaries into forward-looking tools. A buyer who notices a widening gap between announced index changes and actual negotiated rates can lock in terms before the market catches up. That's the difference between reading data as a record and using it as leverage.
FAQ
A mix of things—freight rates remain volatile, energy costs haven't settled, and several key manufacturing hubs are still dealing with labor shortages. On top of that, some countries have adjusted tariffs on raw materials, which feeds straight into landed costs.
When the importing country's currency weakens, each unit of foreign goods costs more in local terms, even if the supplier's price hasn't changed. Importers often try to hedge, but small and mid-sized buyers usually end up absorbing the difference for at least a quarter.
Electronics components, agricultural chemicals, and certain metals like aluminum and copper have been volatile. Pharmaceuticals and specialized machinery tend to move more slowly, but their prices rarely drop once they've climbed.
A few, yes. Some Southeast Asian markets have seen modest declines in consumer goods imports due to oversupply after the pandemic restocking rush. Parts of Eastern Europe have also reported lower prices for certain textiles and basic plastics.
They're often the swing factor. A single container rate change from $2,000 to $6,000 can add 15–20% to the final cost of bulky, lower-value goods. Even when factory prices stay flat, logistics can make an import look much more expensive.
Many are diversifying away from single-country dependence. For example, buyers who relied on one East Asian supplier are now testing Mexico, Turkey, or Vietnam. Others are renegotiating payment terms or buying larger volumes during temporary dips.
Focus on three indicators: container spot rates from major Asian ports, local currency strength against the dollar, and any new trade policy announcements. Those three usually give an early signal before official import price indexes move.
Yes, you can follow free monthly reports from national customs agencies, central bank bulletins, and industry associations. Cross-checking two or three sources helps, since some data lags by 30–60 days.
Conclusion
The gap between published import price indexes and what actually shows up on a buyer's invoice has widened enough that relying on the official numbers is a costly mistake. Freight costs are the obvious culprit. When container rates double or port congestion adds emergency surcharges, the landed price of goods jumps even if the factory gate price hasn't moved. Currency volatility adds another layer: a supplier's invoice may look unchanged in their local currency, but a sudden swing in your own currency can rewrite the cross-border price tag overnight. Then there is regional divergence. Import prices for the same commodity can move in completely different directions depending on whether you are buying in Rotterdam, Houston, or Shanghai, because energy costs, labor availability, and local demand each pull in different ways. None of this shows up cleanly in a broad index.
Beyond tariffs, hidden charges keep inflating import bills quietly. Port handling fees, customs brokerage, inspection costs, demurrage, and last-mile surcharges often appear only after a purchase is booked, so buyers who track only unit prices miss the real trend. Reading import data like a buyer, not a bystander, means stripping out the noise—seasonal spikes, temporary currency blips, one-off supply shocks—and focusing on signals that repeat month after month. That includes sustained freight inflation, a widening regional price spread, or a pattern of extra fees from a particular origin. When you shift from watching indexes to watching total landed cost, import price trends become an early warning system for sourcing decisions. You can renegotiate before a supplier raises rates, or switch origins before a regional bottleneck becomes a crisis. The practical takeaway is simple: published indexes are a rearview mirror, but your import bill is the road ahead. Track the real numbers—freight, currency, regional spreads, and hidden charges—and you will see the price trends that actually matter.
Contact Us
Contact Person: Grace
Email: [email protected]
Tel/WhatsApp: +86 18721992033
Website: https://www.tendata.com